How to Categorize Material Costs for Tax Deductions
Last Updated: November 12, 2026
Quick Summary
Categorize material costs by asking whether you resell the item or build it into a product you sell, whether you consume it on jobs within a year without it becoming part of the finished product, or whether it lasts more than a year and keeps its value. That puts each purchase into one of four buckets: inventory, COGS, supplies, or an asset you depreciate.
- Materials become COGS when the related product or job is sold, not when purchased.
- Supplies are consumables that never become part of what you sell and are deducted in the year you buy them.
- Your COGS formula is beginning inventory plus purchases minus ending inventory.
- Material still on hand at year-end belongs in inventory, not this year's COGS.
- Record the classification at the point of purchase, before the receipt leaves the truck.
Table of Contents
- Start With a Decision Tree for Material Costs
- Supplies vs. Materials for Taxes: The Line That Changes Your Deduction
- Cost of Goods Sold for Small Business: When Materials Become COGS
- How to Track Job Costs Across Crews and Projects
- Set Up a Business Expense Categories Spreadsheet That Matches Your Books
- Worked Examples: Mixed-Use, Returned, and Damaged Materials
- Get Your Material Costs Categorized Before Tax Season
- Frequently Asked Questions
Start With a Decision Tree for Material Costs
Every material purchase falls into one of four buckets. Walking through this decision tree helps owners see how the way you categorize material costs for tax deductions changes when you get the write-off and how much you keep.
Ask three questions in order:
- Will you resell it or build it into a product you sell? If yes, it is inventory or cost of goods sold.
- Will you use it up on jobs within a year, but it never becomes part of the finished product? If yes, it is a supply.
- Will it last more than a year and keep its value? If yes, it is an asset you depreciate.
Most expensive mistakes come from skipping straight to "it's a business expense" without asking which kind.
The Four Buckets: Inventory, COGS, Supplies, or Asset
Inventory is material you hold to sell or to build into something you sell.
Cost of goods sold (COGS) is the cost of materials that actually went into the products or jobs you sold this year.
Supplies are the consumables that keep the business running but never become part of what you sell.
Assets are tools and equipment you will use for more than a year.
The line between these buckets decides deduction timing.
A Repeatable Classification Workflow for Ambiguous Purchases
Step 2: Apply the one-year and part-of-the-product tests. If the item becomes part of what you sell, it is inventory or COGS.
Step 4: Record the classification at the point of purchase. The category goes on the receipt or into the job-costing app before the receipt leaves the truck.
Watch out: the most common gray-area error is buying material in bulk for a discount and expensing the whole purchase immediately.
Worked Examples Across Business Types
Here is how the workflow resolves in four settings.
Contractor. A plumber buys copper pipe, fittings, and a roll of Teflon tape for a repipe job.
Maker. A furniture builder buys hardwood, glue, and finish.
Reseller. An online seller buys a pallet of returned small appliances to resell. The entire purchase is inventory, becoming COGS only when each unit sells.
Service business. A cleaning company buys mop heads, cleaning solution, and trash bags.
Where Material Costs Fit in Your Business Expense Categories
Material costs do not all land on the same line of your books. Inventory and COGS belong in their own section, separate from operating expenses like rent and insurance.
- COGS section: raw materials, freight on materials, direct labor on production
- Operating expenses: supplies, small tools, rent, insurance, vehicle costs
- Asset section: equipment, vehicles, leasehold improvements
Mixing these together is the most common bookkeeping problem we see in the trades. It makes your profit margin look wrong and your tax return harder to defend.
Supplies vs. Materials for Taxes: The Line That Changes Your Deduction
Why does it matter? Timing. Supplies are usually deductible right away. Materials wait until the job or product sells.
A plumber buying copper pipe for a specific install is buying material.
The IRS calls deductible expenses "ordinary and necessary" for your trade, per IRS Publication 535 on business expenses.
Watch out: labeling a big material purchase as "supplies" to grab the deduction early can invite questions.
Cost of Goods Sold for Small Business: When Materials Become COGS
For a small business, cost of goods sold is the total cost of the materials and direct labor that went into the products or jobs you sold during the tax year.
You buy lumber in March and sell the deck in June. The lumber cost hits COGS in June, not March.
Your COGS formula looks like this:
Beginning inventory + purchases - ending inventory = COGS
That is why a year-end count matters so much. Skip it and your COGS is wrong, which means your taxable income is wrong too.
Timing Rules: Unsold Inventory and Year-End Counts
Unsold inventory is not deductible yet. Material sitting in your shop on December 31 is still an asset, not an expense.
A physical count at year-end is the usual way to establish inventory on hand. Walk your storage, count what is on hand, and value it at cost.
A common mistake is counting only big-ticket items. Count everything you would have to rebuy to finish a job. Partial counts create phantom profit.
How to Track Job Costs Across Crews and Projects
Tracking job costs means assigning every material purchase to a specific job, then comparing planned spend against actual spend.
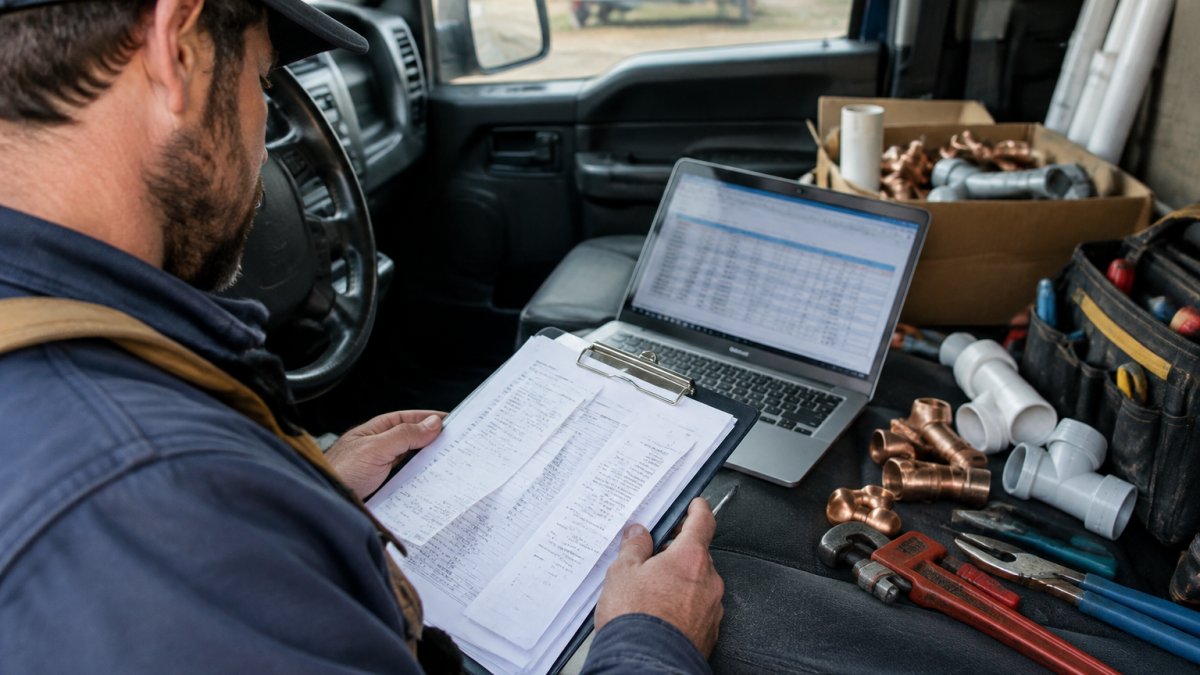
Start with a job number on every receipt.
Then reconcile weekly, not monthly. A ten-minute Friday review catches problems while the job is still open.
For a deeper walkthrough of assigning costs per crew and project, see our guide on job costing for trades.
Set Up a Business Expense Categories Spreadsheet That Matches Your Books
A business expense categories spreadsheet works when its categories match your chart of accounts exactly. If your spreadsheet says "materials" and your books say "job materials and supplies," you have created two systems that will never reconcile.
Build the spreadsheet around the same buckets your bookkeeper uses:
- COGS - Materials
- COGS - Freight In
- Operating - Supplies
One column each for category, job number, receipt total, and vendor is enough to reconcile a month in minutes.
Chart of Accounts Example for a Trades Business
A simple trades chart of accounts might look like this:
| Account | Type | Example Purchase |
|---|---|---|
| Job Materials | COGS | Copper pipe for a repipe |
| Freight In | COGS | Delivery fee on a material order |
| Job Supplies | Expense | Tape, caulk, rags |
| Small Tools | Expense | Under-threshold hand tools |
| Equipment | Asset | Pipe threader, work van |
If you are building this from scratch, our walkthrough on setting up a chart of accounts for contractors shows the exact account structure to copy.
The threshold for expensing small tools instead of depreciating them is a real decision, not a rounding call. Many owners set an internal cutoff and apply it consistently. Check current IRS guidance on de minimis safe harbor for tangible property before you set yours.
Worked Examples: Mixed-Use, Returned, and Damaged Materials
Real purchases rarely arrive neatly labeled. Here is what to do when a single receipt covers business and personal use, when material comes back, when it is ruined before use, and when a job burns more material than planned.
Mixed-Use Purchases
An electrician buys a 500-foot spool of wire for a job and uses the leftover on a personal project at home. Split the receipt by job and by personal use, and deduct only the business portion.
Watch out: do not leave the personal portion sitting in a business expense account because the amount is small. Small, undocumented personal charges are exactly what an examiner looks for when reconstructing a year.
Returned Materials
You buy a box of fittings, return half, and get a supplier credit. The return reduces your material cost, not your income.
A common pattern is recording supplier credits as miscellaneous income because they arrive as a check or card refund. That overstates income and understates job cost at the same time. Match the credit to the original purchase line instead.
Damaged Materials
Material ruined before use is generally still deductible, but the deduction depends on documentation. Note what was damaged, when, and why, and keep a photo with the receipt.
For bookkeeping, move the damaged material out of inventory or job cost and into a clearly labeled damaged or scrap expense account. That keeps the loss visible and keeps it from being buried in a job that otherwise looks profitable.
Wasted Overruns and Job Waste
A job that runs over on material is a margin problem first and a tax problem second. Track the overrun against the job to see which jobs consistently burn extra material and price the next one better. Normal waste like cutoffs and breakage stays in job cost; abnormal waste, like a crew cutting to the wrong size and reordering, deserves its own line so it does not disappear into the job's material total.
For a closer look at how overruns hit your margins, read tracking material overruns and project margins.
Year-End Cleanup for These Scenarios
Before the year closes, confirm personal-use portions are out of business expenses, supplier credits are matched to the original purchase rather than booked as income, damaged and scrapped material sits in its own expense account with documentation, and abnormal job waste is separated from normal job cost. Each takes minutes at year-end if entries were made when the event happened, and hours if they were not.
Get Your Material Costs Categorized Before Tax Season
Categorizing as you go can make filing season a review rather than a search through a year of receipts.
Here is a checklist to run before the year closes:
- Reconcile every material purchase to a job or an inventory account
- Complete a physical year-end inventory count at cost
- Confirm small tool purchases are coded consistently against your threshold
If material categorization is one piece of a bigger filing push, our 2026 tax season prep guide for contractors covers the full checklist. And if you would rather hand the whole thing off, our outsourced bookkeeping for small trades service takes material and expense categorization off your plate.
The IRS publishes Publication 334, the small business tax guide as a plain-language reference for sole proprietors working through Schedule C, including the Part III section where COGS gets reported.
Checkpoint Bookkeeping closes books for home service businesses within 10 business days, with a dedicated bookkeeper and no offshore handoffs. You get clean, understandable profit and loss and balance sheet reports every month. Fixed monthly pricing means no surprise invoices.
Get started with Checkpoint Bookkeeping to see how your books can be reconciled and closed ahead of tax season.
Frequently Asked Questions
Can you write off the cost of materials on your taxes?
Yes, but the timing and category depend on what the materials are for. Materials used to produce or install a product you sell are usually recovered through cost of goods sold when that job is billed. Materials consumed in day-to-day operations, like sandpaper or solder, are typically deducted as supplies in the year you buy them. Materials bought for a specific customer job are deducted when the job is completed and invoiced. Keep receipts and invoices tied to each job so the deduction is easy to support.
Should materials be categorized as supplies or cost of goods sold?
Ask one question: does the material become part of what the customer pays for? A water heater installed in a customer's home is COGS. The Teflon tape and screws used during that install are supplies. This supplies vs. materials for taxes distinction matters because COGS is tied to revenue timing while supplies are deducted when purchased. Misclassifying both directions inflates or defers your deductions, which is why a consistent chart of accounts and a clear decision rule save hours at year end.
Can unused materials be deducted in the year they are purchased?
Generally no, if those materials are inventory held for resale or production. Under standard inventory accounting, unsold inventory stays on your balance sheet until it is sold or used, and a year-end count sets the number. Small businesses using the cash method may have more flexibility, but the rules depend on your accounting method and revenue. Track leftover materials separately, count them at year end, and confirm the treatment with your CPA before filing Schedule C.
What records should a small business keep for material expenses?
Keep the receipt or invoice for every purchase, plus a note on which job or category it belongs to. For contractors, that means purchase orders, supplier invoices, and job cost sheets that tie materials to a specific address or work order. Store returned-material credits and damaged-material write-offs alongside the original purchase. A business expense categories spreadsheet or bookkeeping system that matches your chart of accounts makes reconciliation fast and keeps everything audit-ready when your CPA asks for backup.
